26 Jun 2026
Ecommerce in H2: Forecasts and growth strategies
By Ellie-Rose Davies, Content Manager at IMRG
In this blog we look at eCommerce in H2, sharing what's happened throughout the year so far and what's to come next, with predictions and growth strategies from industry experts.
Inside this blog:
- IMRGs H1 overview (thus far)
- Reacting to changing demand
- Preparing for AI
- Understanding your customers
- Reducing checkout friction
- Improving fulfilment and delivery
IMRGs H1 overview (thus far)
The first half of 2026 has been a mixed for UK online retail. While growth was more subdued between February and April, the market is now in its fifth consecutive week of year-on-year growth (as of w/c 14th June), according to IMRG's Online Retail Index, derived from over £30bn of UK online retail spend. This growth likely owes to the late-May heatwave, as well as welcoming the start of the FIFA World Cup. Though now with sustained hot weather in June, can we expect the end of H1 to end on a high, or as Andy noted in our new podcast episode*, is the online sector better to see fluctuations in weather to drive consumer demand? *IMRGs podcast episode: IMRG Takes On The British Weather When reviewing H1 events, it's important to remember that both Easter and Mother's Day fell on different dates compared with 2025, creating expected peaks and troughs in retailers weekly data. Average basket value has remained around the £130 mark throughout 2026, but since Mothers Day in March, it has tracked above 2025 levels, at around £140. At a category level, Clothing continues to face challenging trading conditions, although Footwear is now in its twelve consecutive week of year-on-year growth, as of w/c 14th June 2026. Seasonal events also drove strong performance, with Father's Day boosting Fragrance (+54.8% YoY) and Menswear (+6.3% YoY), while gifting performed well across both Mother's Day and Father's Day. With H2 fast approaching, we asked industry experts for their outlook on the trends and strategies set to shape the remainder of 2026.Reacting to changing demand
The first half of the year has shown just how quickly trading conditions can change. From shifting seasonal events to weather patterns and the World Cup, retailers have needed to respond to changing demand rather than rely on historical trends. Looking ahead, that flexibility is likely to remain just as important. As noted by Bradley Hall, Performance Director, Shoptimised, H2 will be shaped less by what happened last year and more by how retailers react to what is different this year. The World Cup could shift buying behaviour and peak trading times, while geopolitical uncertainty and delayed holiday bookings may mean fewer people are in the UK shopping during key periods. Bradley argues that The biggest opportunity is to stay flexible. Move budget around based on where demand actually is, not where it was last year. Though historical data still matters, it should be used as a guide alongside what is happening in the market right now.Rethinking promotions
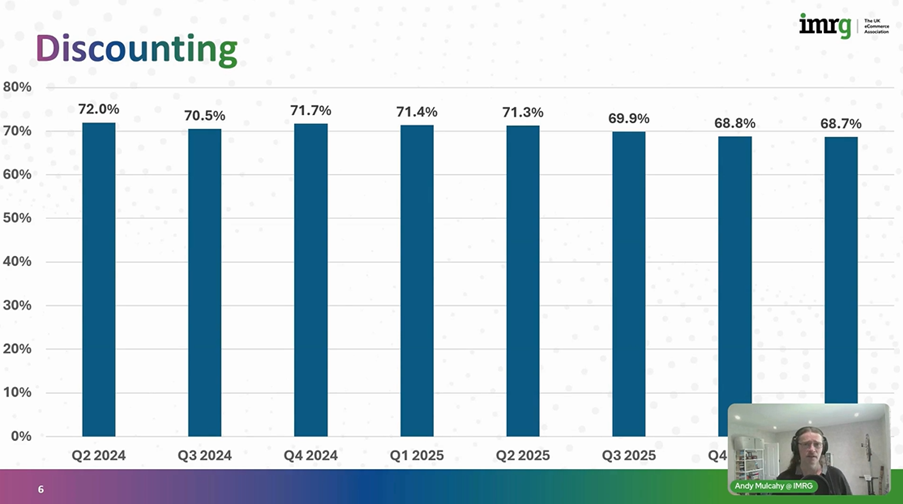
IMRG Online Index data shows the percentage of products that are being sold with some kind of discount against them, this could be a sitewide discount or some kind of code that activates a percentage off the sale. The data shows that a considerably high number of products are sold with a discount “ typically around 71-72%. Though, since Q4 2025 and during Q1 2026 we have seen the rate decline ever so slightly, to just below 70%.
Source: IMRGs Online Retail Index, presented on The IMRG Show #279
Retailers may be starting to see the value of using more targeted and creative promotions, rather than simply offering bigger discounts. Speaking on this is Dan Bond, VP of Marketing, RevLifter who shares, H2 performance will largely be shaped by how well retailers understand their own audiences. The summer months offer a useful window to build that picture. Which visitors convert without any intervention? Which ones respond to a specific type of offer? Which ones are just browsing? Dan notes that this kind of insight changes how you approach peak season, shifting the focus from volume of promotions to relevance of promotions. Margin pressure is likely to be a defining theme in H2, and retailers who address that proactively rather than reactively will be better placed when Q4 demand picks up, says Dan. Similarly, expert Talon.One says, Promotions, done well, are not a margin drain. They are a relationship-building mechanism. The opportunity heading into H2 is clear. Retailers that continue to default to simple percentage-off mechanics are leaving brand-building potential on the table, especially as gamified formats gain ground fast. Talon.One tell retailers to Stop treating discounting as a default and start treating it as a design decision. Not all discounts are equal. Their research found that a 'second pair 50% off' offer scored more than twice as highly as a flat '15% off' in consumer testing. The reason is engagement: the structured mechanic keeps the customer shopping, increases basket size and preserves the full-price anchor on the first item. Promotions are only one piece of the puzzle, however. As AI continues to reshape how consumers discover and evaluate products, retailers are also being challenged to rethink the product experience itself.